Leveraging Mathematics and AI to Trade & Build
I design, backtest, and automate systematic trading strategies. As a Quantitative Researcher, I work at the intersection of quantitative finance, machine learning, and data-driven research, with a growing focus on Generative AI and LLM Engineering for building production-grade intelligent systems.
About Me
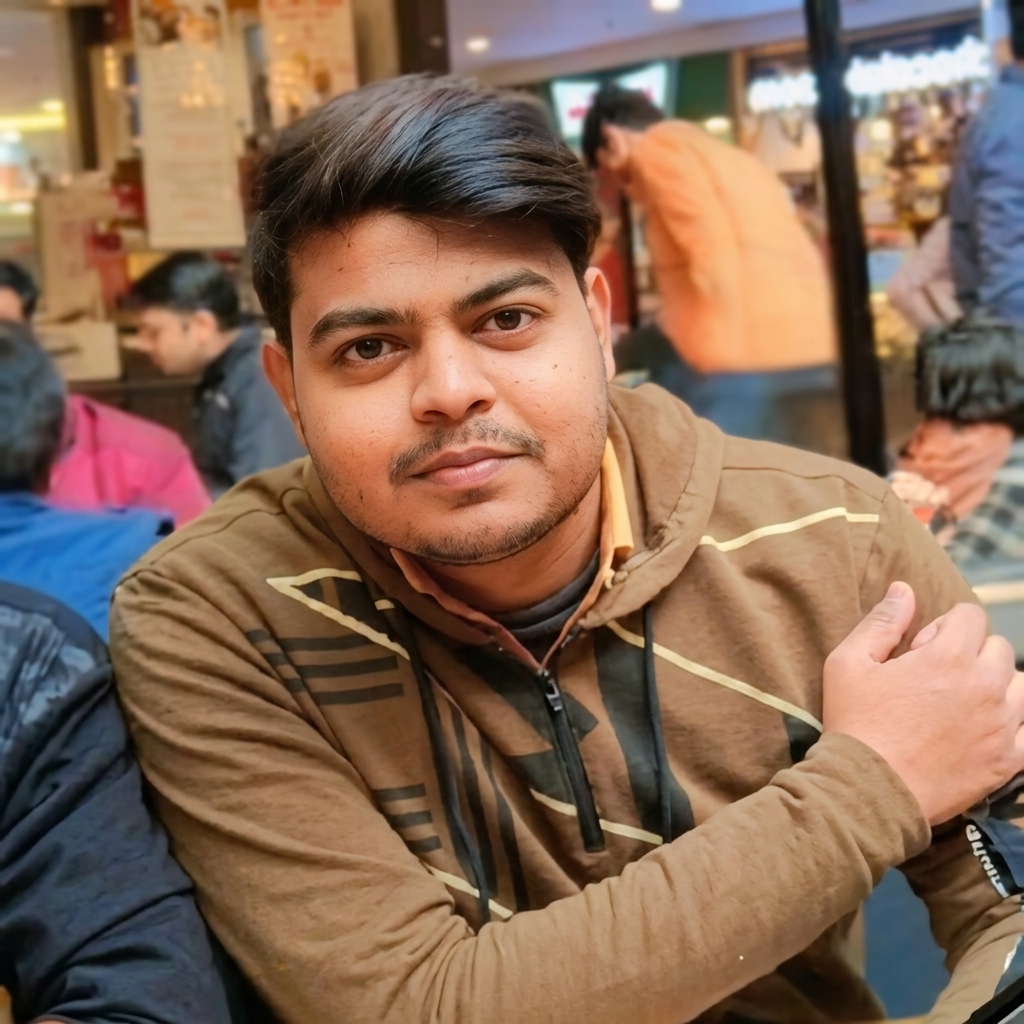
Aarish Khan
Jr. Quantitative Researcher
Pace Stock Broking Services Pvt. Ltd.
My Journey
I work as a Junior Quantitative Researcher at Pace Stock Broking Services, where I spend my days building backtesting pipelines, validating alpha strategies, and engineering data flows. My professional background began in the trading pits as an Equity & Derivatives Trader, giving me first-hand experience with execution systems, derivatives math, and market microstructure.
With a formal background spanning Economics (B.A.), Law (LL.B.), and an ongoing Master of Computer Applications (MCA), I occupy a unique sweet spot at the intersection of business logic, computational engineering, and strategic modeling.
I am currently expanding my skill set to build scalable AI systems, specializing in Generative AI architectures, vector databases, and MLOps pipelines.
Technical Toolkit
Quantitative Finance
- Backtesting & Strategy Dev
- Time Series & Risk Analysis
- Derivatives & Options Math
- OHLCV Data Engineering
- Execution Architecture
Artificial Intelligence & ML
- Neural Networks (ANN/CNN)
- Supervised & Unsupervised ML
- Large Language Models (LLMs)
- PyTorch, TensorFlow, Scikit-learn
- Streamlit AI Application Dev
Data & Software Engineering
- Advanced Python & SQL
- Pandas, NumPy, Matplotlib
- GitHub Actions & CI/CD Cron Jobs
- SQLite & Relational Databases
- RESTful API Integration
Featured Projects
Tick-Level Option Hedging Simulator
A client-side options trading simulator built to backtest and execute hedging strategies using historical tick-by-tick (second-wise) bid/ask data. It streams historical option chain datasets chronologically, allowing users to execute paper trades, adjust strike positions, and simulate dynamic portfolio hedging.
- Runs on historical second-wise tick data streams.
- Delta Breach Auto-Pause triggers automated pauses for portfolio re-hedging.
- Real-time calculation of LTP, MTM PnL, Net Value, and portfolio Delta.
- Interactive trade history drawers and session logging.
Quant-AI Strategy Copilot
A topmost, semi-transparent desktop overlay assistant. It allows users to ask quantitative trading questions via microphone/speaker audio capture, manual text typing, or by grabbing screen captures of charts and formulas directly from research PDFs or terminals.
- Low-Latency Signal Pipeline
- Windows screen capture OCR (DeepSeek/Groq)
- Multi-threaded Python engine with Win32 hooks
ShoonyaOHLC AutoSync Pipeline
An automated data engineering pipeline that auto-fetches daily post-market Nifty Spot, Futures, and Options OHLC values from the Shoonya API, structures it, and uploads the dataset to cloud-based storage.
- Run via GitHub Actions cron jobs
- Google Drive cloud upload integrations
- Scalable CSV directory for backtests
Customer Churn Prediction (ANN)
An Artificial Neural Network (ANN) model built in TensorFlow and deployed as a Streamlit web application. Predicts whether retail bank customers are likely to exit the bank based on demographics and financial metrics.
- Multi-layer ANN with hyperparameter tuning
- Preprocessing pipeline with categorical encoding
- Real-time prediction web UI
Live/Paper Strategy Execution Engine
A systematic execution engine tracking strategy status in real time. It uses SQLite databases to save local trading states, active variants, order executions, and trade logging for low-frequency algorithmic strategies.
- Relational database logging schemas
- Paper & Live trade state comparisons
- Modular order structure logging
Let's Collaborate
Get in Touch
I am open to opportunities in Quantitative Research, Machine Learning Engineering, and Generative AI roles. If you want to talk systematic trading strategies, LLM agents, or check out my code, feel free to reach out.